
Blogs
PW Consulting: Turbomolecular Pumps Market to Hit USD 2,460M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-30
Turbo Molecular Pumps Market — 2026 Strategic Preview
By PW Consulting — Senior Strategic Advisor / Head of Industry Analysis
This briefing frames the strategic decisions that matter in 2026 for executives operating in or adjacent to the turbomolecular pumps market. Drawing on our PW Consulting market model (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) and primary research across OEMs, integrators and end-users, this preview highlights where value will accrue, where risk is concentrating, and which tactical moves buy time versus create durable advantage. The purpose is to demonstrate technical and commercial depth while reserving core segmented datasets for the full report.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Market snapshot — macro trajectory you can act on
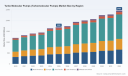
The turbomolecular pumps market reached approximately USD 1.69 billion in 2025 and is forecast to grow at a steady compound annual growth rate of about 5.5% over the 2026–2032 period, reaching roughly USD 2.46 billion by 2032 under our base scenario. After a measured recovery from 2020–2023, the market experienced an acceleration in 2024 and 2025 driven by capacity build-outs in semiconductor and advanced materials processing, and the maturation of higher-throughput maglev and hybrid solutions. Market concentration is meaningful: the top three vendors account for a majority share of revenue, and the top five raise that concentration modestly further — an important structural feature for pricing dynamics, aftermarket opportunity and M&A playbooks.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Key demand & supply dynamics shaping 2026 decisions
-
Policy and procurement are now technical levers. Energy-efficiency directives in major jurisdictions have already pushed OEMs to deliver lower-wattage drives and intelligent standby modes. Public-sector procurement and large-system integrators are explicitly scoring energy intensity and lifecycle emissions, creating a near-term bid advantage for pump platforms with validated efficiency credentials.
Turbo Molecular Pumps (Turbomolecular Pumps) Market -
Net-zero roadmaps impose multi-year product and capital cycles. Net-zero energy-intensity requirements in Europe and North America extend planning horizons for manufacturers (multi-year compliance windows), forcing choices between incremental efficiency upgrades and more fundamental architecture changes (e.g., wider adoption of magnetic levitation and smart power electronics).
-
Semiconductor and life-science ecosystems are demand multipliers. Policy stimuli and domestic fab programs are sustaining demand for higher pumping speeds and lower base pressures in select submarkets; procurement timelines and qualification hurdles remain long, making early engagement and co-development with strategic customers a high-return activity.
-
Raw-material and component risk is concentrated but manageable. Bearings made from advanced stainless steels such as Cronidur 30 extend service life and lower total cost of ownership, but rare-earth magnet supply risk for maglev rotors is prompting design responses — dual sourcing, magnet-reduced rotor concepts and increased tolerance for lower dysprosium content.
Technology trajectories and product strategy
-
Magnetic levitation versus mechanical bearings. Maglev platforms continue to advance performance, reliability and maintenance economics; however, they introduce different supply-chain exposures (rare-earth magnets, specialized power electronics). Mechanical (oil-lubricated and ball-bearing) architectures remain attractive for certain industrial coatings and retrofit niches because of lower upfront cost and established service networks.
-
Hybrid architectures as a pragmatic bridge. Hybrid designs that combine elements of maglev control with mechanical resilience are emerging as a strategic compromise for customers unwilling to accept full maglev life-cycle trade-offs immediately.
-
Software and systems matter as much as spinning hardware. Digital features — predictive maintenance, remote diagnostics, and intelligent standby — now materially affect procurement choices. OEMs that bundle proven software services alongside validated power-efficiency metrics capture higher aftermarket revenue and improve retention.
Supply chain and cost resilience — what to prioritize now
-
Dual-source critical magnets and bearings. Short-term supplier diversification for rare-earth magnets and advanced stainless alloys is a high-payoff defensive move. Firms should invest in audited second-source qualification and flexible bill-of-materials testing.
-
Vertical or contractual integration for power electronics. Control boards and motor drives are an underappreciated source of differentiation. Securing capacity or preferred pricing for advanced inverter components reduces time-to-market risk for new maglev platforms.
-
Aftermarket and service-first strategies. With replacement cycles longer but service margins higher, developing modular upgrade kits (efficiency retrofits, maglev upgrade paths) and standardized field-service training yields durable margin expansion.
Competitive landscape — who to watch and why
The field is characterized by a mix of established vacuum OEMs and technology-led entrants. The following firms are active players we tracked closely; each has distinct strategic strengths that make them potential partners, competitors or acquisition targets depending on your objectives:
-
Edwards Vacuum — Burgess Hill, United Kingdom — https://www.edwardsvacuum.com. Strengths: broad mechanical turbomolecular ranges (nEXT and STP series) and expanding maglev offerings; notable go-to-market across industrial and analytical segments. Recent visibility at Analytica 2026 underscores channel engagement and field validation efforts.
-
Pfeiffer Vacuum — Aßlar, Germany — https://www.pfeiffervacuum.com. Strengths: comprehensive TURBOPUMPS portfolio spanning mechanical, magnetic and hybrid bearings with strong positioning in high/ultra-high vacuum applications and systems integration capability.
-
Ebara Corporation — Tokyo, Japan — https://www.ebara.com. Strengths: high-throughput maglev turbopumps and strong manufacturing throughput; emphasis on performance and throughput metrics for industrial customers.
-
Leybold — Cologne, Germany — https://www.leybold.com. Strengths: robust TURBOVAC i/iX family tailored to industrial coating and research use-cases; recent product expansion signals continued focus on hardening designs for tough working environments.
-
ULVAC — Chigasaki, Japan — https://www.ulvac.com. Strengths: desktop and mid-range maglev and ball-bearing series with channel focus in Asia; modular product platforms that appeal to OEM integrators.
-
Agilent Technologies — Santa Clara, CA, USA — https://www.agilent.com. Strengths: analytical and research-grade high-vacuum turbo pumps backed by broad customer relationships in instruments and laboratories.
Recent market signals
-
Edwards Vacuum showcased nEXT and STP series alongside T-Station pumping solutions at Analytica 2026 — a signal of continued investment in channel demonstration and turnkey pumping solutions (March 2026).
-
Leybold expanded its TURBOVAC i/iX family with robust variants aimed at industrial coating and research applications — a reminder that ruggedized mechanical platforms retain clear niche relevance (March 2026).
Strategic playbook for 2026 — actions by role
-
OEMs: Prioritize a three-track product roadmap: immediate low-power drive retrofits, medium-term maglev proliferation with supply-chain hardening, and long-term platform redesigns that lower lifecycle emissions. Pair product launches with service bundles to capture recurring revenue.
-
Component suppliers: Move from spot-selling into co-development agreements for bearings and magnet systems. Offer qualification packages and extended warranties to shorten OEM certification cycles.
-
Systems integrators and large end-users: Lock multi-year service contracts and negotiate upgrade credits tied to energy-efficiency performance. Early engagement in OEM R&D roadmaps reduces qualification risk and shortens adoption timelines.
-
Private equity and corporate development teams: Look for tuck-in opportunities in aftermarket services, software-enabled maintenance platforms, and regional service centers to leverage the concentrated market structure and aftermarket margins. Use buy-and-build plays to capture retrofit demand.
What PW Consulting’s full report delivers (practical modules)
-
Detailed market sizing and 2026–2032 forecasts with scenario and sensitivity analyses, including upside and downside demand drivers.
-
Segment-level demand maps (by region, product architecture, and application) and prioritized TAM/SAM/SOM frameworks for commercial planning.
-
Vendor benchmarking with product matrices, technology scorecards, go-to-market positioning, and aftermarket revenue models.
-
Supply-chain risk register (critical components, second-source options, and cost-inflation scenarios) and an implementation playbook for mitigation actions.
-
Commercial playbooks: pricing levers, qualification pathways for semiconductor and life-science customers, RFQ templates, and retrofit upgrade pricing guide.
-
M&A and partnership screening toolkits with candidate lists, valuation guardrails, and integration risk checklists.
Concluding perspective
The turbomolecular pumps market in 2026 is neither nascent nor fully commoditized — it sits in a phase where technical differentiation (bearing architecture, electronics, and software) and regulatory-driven efficiency credentials meaningfully influence commercial outcomes. Firms that move early to secure critical materials, offer service-forward total-cost-of-ownership propositions, and align roadmaps with public-sector energy/CHIPS-driven demand will create asymmetric returns. PW Consulting’s full study provides the granular segment-level maps, vendor scorecards and executable playbooks executives need to prioritize investment and M&A through 2026 and beyond.
To access the complete dataset, supplier scorecards, and the operational playbook referenced above, contact PW Consulting or visit our report portal for licensing and tailored advisory options.
For detailed analysis of this topic, please visit the official page: Turbo Molecular Pumps (Turbomolecular Pumps) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV & Fuel Cell Vehicles Market to Reach USD 539B by 2032
By pmarketresearch, 2026-07-30
Electric Vehicles and Fuel Cell Vehicles Market — Strategic Insights for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concentrated briefing that translates our latest Electric Vehicles (EV) and Fuel Cell Vehicles (FCEV) Market study into immediate strategic value for executives planning 2026 moves. This piece follows a “trailer” approach: it surfaces the analytical rigor and directional findings you need to judge relevance, while preserving the granular segmented datasets and proprietary models that are accessible in the full report.
Electric Vehicles and Fuel Cell Vehicles Market
Executive snapshot — the market in context
Our analysis uses 2025 as the base year, reviews historical trends from 2020–2025, and models a 2026–2032 forecast horizon. The combined EV + FCEV market has transitioned from an emerging growth phase into a structural build-out: from roughly USD 163 billion in 2020 it expanded to about USD 215 billion by 2025, and our baseline forecast projects the market to surpass USD 500 billion by the early 2030s. The modeled compound annual growth rate (CAGR) for the forecast window is 14.06%, reflecting sustained demand, vehicle electrification momentum, and progressive technology cost curves.
Electric Vehicles and Fuel Cell Vehicles Market
These headline numbers frame several practical implications for corporate strategy in 2026: the market is large enough to justify scale investments but still diffuse enough that differentiated plays, partnerships and selective vertical integration can materially change competitive positions.
Electric Vehicles and Fuel Cell Vehicles Market
Why this research matters for 2026 decision-making
- Timing and investment calibration:
With double-digit structural growth baked into our baseline, firms must decide in 2026 whether to accelerate capital deployment (manufacturing, assembly lines, hydrogen fueling partnerships) or to stage investments to capture margin improvement from technology learning curves. The market trajectory supports aggressive scaling for players who can reduce unit costs quickly; it also rewards targeted pilots for those prioritizing route optimization and customer experience.
- Product and portfolio choices:
Automakers and fleets face trade-offs among battery-electric, fuel-cell, and hybrid platforms. Regulation-driven affordability initiatives and shifting consumer segments mean product roadmaps should be optimized not only on unit economics but also on lifecycle emissions compliance and total cost of ownership at the fleet level.
- Supply chain de-risking:
Raw material and component cost targets announced by governments and industry bodies — including fuel cell cost milestones and hydrogen production targets — create actionable procurement triggers. 2026 is the year to lock multi-year agreements, qualify secondary suppliers, and invest in recycling or substitution research to mitigate PGM exposure and upstream bottlenecks.
- Regulatory and market-access playbooks:
New CO2 standards, incentive rebalances and regional policy shifts have made market-entry conditional on well-orchestrated pricing and compliance strategies. Positioning product variants to meet affordability thresholds and navigating region-specific registration dynamics are critical tactical priorities for 2026 launches.
What the report delivers — practical, decision-ready outputs
- High-fidelity market sizing and 2026–2032 forecasts (including scenario and sensitivity analyses).
- Actionable go-to-market roadmaps for OEMs, Tier-1 suppliers, fleet operators, and infrastructure investors.
- Technology and cost trajectories (battery, fuel cell stacks, power electronics, hydrogen handling) with break-even timelines and unit-cost ladders.
- Supplier and partner heatmaps, including capability matrices to expedite procurement and JV screening.
- Regulatory and incentives tracker mapped to commercialization milestones and launch windows.
- Investment case templates, M&A screens, and financial models calibrated to risk-adjusted returns under alternate adoption curves.
- Field-tested pilot blueprints, procurement clauses, and go/no-go decision checkpoints for 0–24 month programs.
Note: the report includes full regional and application segmentations and the underlying datasets that support these deliverables; selective high-level figures and trends are presented here to demonstrate methodological rigor while preserving the proprietary segmentation tables for report subscribers.
Competitive landscape — companies to watch in 2026
- Toyota Motor Corporation (Toyota City, Japan)
Strategic posture: Toyota continues to play a foundational role in fuel-cell commercialization, leveraging product iterations and system-level engineering to expand applicability across passenger, commercial and heavy-duty segments. The company’s announcement of a third-generation fuel cell system slated for multi-region rollout underscores a push to improve durability and lower lifecycle costs. For competitors and partners, Toyota’s scale and system know-how make it both a potential collaborator and a benchmark for component reliability.
- Hyundai Motor Company (Seoul, South Korea)
Strategic posture: Hyundai’s broad product set — spanning passenger vehicles to hydrogen trucks and buses — positions it to capture diverse hydrogen demand pockets. The refresh cycles for fuel-cell models and commercial vehicle developments suggest a playbook focused on platform reuse and aftermarket services as levers to monetize hydrogen ecosystems.
- Honda Motor Co., Ltd. (Tokyo, Japan)
Strategic posture: Honda’s move to produce plug-in fuel cell variants in the U.S. signals an emphasis on localized manufacturing and market-specific product adaptation. This highlights an operational theme for 2026: OEMs that marry regional production footprints with local policy engagement can accelerate market access while containing logistics costs.
- BMW AG (Munich, Germany)
Strategic posture: BMW’s planned series production of fuel-cell vehicles, leveraging collaborative technology pathways, reveals a risk-managed approach to hydrogen. By combining licensing/partnered technology with scaled manufacturing intent, BMW illustrates an approach suited to premium segments where value capture can justify higher early-cycle costs.
- Nippon Shokubai Co., Ltd. (Tokyo, Japan)
Strategic posture: Component and catalyst innovators are critical enablers of cost reduction. Advances in platinum-group-metal-free catalysts and related materials science are a lever for industrial players to outflank raw-material constraints and to reduce stack costs — an outcome that materially affects heavy-duty total cost equations.
Complementing these OEM and supplier dynamics, product expansions from specialist suppliers (hydrogen recirculation, blowers, system integrators) are sharpening the ecosystem, creating new supplier niches and partnership options. The market concentration metrics indicate a relatively unconsolidated landscape, providing opportunities for agile entrants and focused consolidations.
Industry dynamics and critical external signals
- Policy acceleration: Tighter CO2 standards and region-level mandates are reshaping pricing and portfolio decisions; affordability-driven product introductions are increasingly important.
- Adoption scale: Global electric car sales hit record volumes in 2025, reinforcing electrification as mainstream; this scale validates network and after-sales investments.
- Cost targets: Public-sector technology targets for fuel cell stack costs and hydrogen production create clear commercial inflection points — hitting those targets materially improves heavy-duty and long-haul business cases.
- Localized friction points: Early signs of registration slowdowns in some FCEV registries highlight the need to pair vehicle launches with refueling infrastructure and customer value propositions.
Scenario planning — triggers that change the game
- Base case: Realization of the modeled CAGR and infrastructural rollouts in line with public targets; gradual cost declines enable broadening commercial adoption.
- Upside case: Faster-than-expected hydrogen production cost reductions and accelerated fuel-cell cost improvements unlock rapid heavy-duty electrification and industrial-scale fleet conversions.
- Downside case: Raw-material shocks, slower infrastructure scaling, or policy reversals compress adoption rates and push ROI timelines beyond early investors’ thresholds.
Concrete 2026 actions — prioritized
- Immediate (0–12 months):
Secure supply hedges for key materials, finalize pilots with targeted fleet partners, and lock conditional offtake or offtake-linked financing for infrastructure projects. Use modular procurement templates to speed RFP cycles while retaining flexibility for design evolution.
- Near-term (12–36 months):
Scale production in regions where regulatory and cost conditions align, negotiate technology partnerships for stack and system integration, and build bundled service offerings (vehicle + refueling + telematics) to improve payback for fleet customers.
- Strategic (36+ months):
Pursue consolidation in targeted supplier segments, vertically integrate critical modules if warranted by scale economics, and consider cross-sector alliances to accelerate hydrogen supply and amortize infrastructure investments.
Final word — using this research in 2026
The 2026 strategic window is defined by a large and fast-growing total market, significant technology milestones within reach, and uneven but accelerating infrastructure development. PW Consulting’s EV & FCEV Market study equips decision-makers with the scenario-based forecasts, cost curves, supplier maps and executable playbooks needed to convert market opportunity into competitive advantage. If your 2026 decisions involve capacity commitments, product launches, M&A, or infrastructure investments, the full report will provide the segmented forecasts, model inputs and executable templates to move from intent to impact.
To access the complete datasets, regional and application breakdowns, and the operational toolkits referenced above, please consult the PW Consulting EV & FCEV Market report page or contact our advisory team to arrange a briefing and licensing of the full analytical package.
For detailed analysis of this topic, please visit the official page: Electric Vehicles and Fuel Cell Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Guns Market to Hit USD 2,185.8M by 2032 at 4.3% CAGR
By pmarketresearch, 2026-07-30
Heat Guns Market 2026 Strategic Brief: Why This Report Will Shape Your Decisions
Executive summary
As strategic decision-makers prepare plans for 2026, understanding the structural trajectory of the heat guns market is no longer optional — it is mission critical. PW Consulting’s latest market research uses a 2025 base year and a 2026–2032 forecast window to map a market that has moved from recovery into structurally supported expansion. Our topline model places the global market at approximately USD 1,613.6 Million in 2025 and projects it to reach roughly USD 2,185.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.3% across the forecast period. Historical trends from 2020 through 2025 show steady expansion with episodic volatility tied to macro cycles and supply-side shocks — context that underpins our forward scenarios.
Heat Guns Market
Beyond raw growth, market structure matters. Competitive concentration is meaningful: the three largest manufacturers control a clear majority of industry revenue, while the five largest firms account for an even larger share. This dynamic creates both barriers and levers for incumbents and challengers — scale delivers distribution and R&D advantages, while pockets of fragmentation leave room for targeted disruption.
Heat Guns Market
What the PW Consulting report delivers (practical, actionable content)
This study is designed for executives, corporate development teams, product leaders, and commercial strategists who need immediately actionable insight rather than academic description. Key deliverables include:
Heat Guns Market
- Robust market sizing and forecasting models (base year 2025; forecast 2026–2032) with transparent assumptions and scenario variants (baseline, upside, downside).
- Proprietary demand-driver decomposition that links end-market activity, channel shifts, and technology adoption to volume and revenue outcomes.
- Competitive benchmarking across product capabilities, channel reach, and non-price propositions (warranty, service, digital features).
- Commercial playbooks for product portfolio optimization, channel segmentation, pricing strategies, and after-sales monetization.
- Supply chain and cost-structure maps highlighting supplier concentration, single-sourcing risks, and relocation options.
- M&A target screening and value creation templates for bolt-on and roll-up scenarios, together with integration risk checklists.
- Regulatory and safety compliance matrix with jurisdictional triggers and cost-to-compliance estimates.
- Excel-based sensitivity tools and slide-ready strategic roadmaps that can be adapted to corporate constraints and investment horizons.
We intentionally present synthesis, strategic implications, and diagnostic tools in this brief; detailed subsegment-level datasets (by type, application, and region), including granular percentage splits and downloadable tables, are reserved for the full report and our client portal.
Strategic implications for 2026 decision-makers
The macro trajectory (CAGR 4.3% to 2032) and the concentration profile produce a set of strategic priorities you should adopt immediately if you want to convert market tailwinds into durable advantage:
- Prioritize product differentiation linked to professional use-cases. Growth is being driven by professional and industrial demand that values robustness, temperature precision, and serviceability. Commodity models will face margin pressure — invest selectively in features and extended warranties that create lock-in.
- Accelerate cordless and energy-efficiency roadmaps. Advances in battery chemistry and motor efficiency are enabling cordless form factors that are attractive to professional users and retrofit channels. Early movers who combine battery systems with proprietary thermal control software capture premium price points.
- Design channel strategies for dual distribution models. The market favors both traditional distributor networks (professional/industrial buyers) and big-box/DIY channels. Successful firms maintain differentiated SKUs, pricing ladders, and logistics playbooks for each channel rather than a one-size-fits-all approach.
- Monetize after-sales services and consumables. Consumable elements (nozzles, filters), maintenance contracts, and rapid-replacement programs are low-effort levers to increase lifetime value in a market where product cycles are measured in years.
- Use M&A to fill capability gaps, not just revenue. With top players holding a majority of market share, disciplined bolt-ons that add battery expertise, heat-control electronics, or service networks often unlock more value than horizontal roll-ups alone.
- Fix supply-chain resilience as a strategic objective. Raw-material swings and component shortages materially affect lead times. Dual-sourcing strategies, near-shore options, and inventory-as-a-service should be stress-tested in 2026 budgets.
- Embed sustainability and safety in product roadmaps. Regulatory scrutiny and procurement preferences are shifting to lower embodied energy and safer end-of-life profiles. These are not compliance costs alone — they are differentiators.
Competitive landscape: what the leading manufacturers are signaling
Our competitive analysis profiles the major incumbents and their strategic postures. Across the landscape, several consistent patterns emerge:
- Large global tool OEMs — including established players headquartered in Japan, Germany, and the United States — leverage strong channel partnerships and broad product portfolios to defend professional and consumer demand. Their assets include scale manufacturing, recognized brands, and deep distribution.
- Specialist manufacturers — focused on hot-air technology and professional applications — compete on thermal control, ergonomics, and service propositions. For many buyers, product-level performance and trusted durability trump headline price.
- Newer entrants and regional specialists — particularly those emphasizing cordless and energy-efficient designs — are using narrow product differentiation and aggressive channel partnerships to gain footholds.
Company-level strategies that matter in 2026:
- Invest in cordless ecosystems: firms that can pair heat guns to a common battery platform across tools create cross-selling synergies and higher customer switching costs.
- Optimize aftermarket revenue: warranty extensions, consumables, and service contracts are practical routes to margin expansion even in mature segments.
- Leverage distribution intelligence: real-time channel analytics and differentiated SKUs per channel reduce stock-outs and deepen shelf presence.
For organizations evaluating partnerships, licensing, or acquisition targets, our report includes an executable matrix that ranks prospective counterparties by technology fit, geographic reach, and integration complexity.
Risks and leading indicators to monitor through 2026
Strategic planning must be scenario-ready. Monitor these leading indicators closely to recalibrate decisions mid-course:
- Battery and component cost curves — significant improvements will accelerate cordless adoption and compress price elasticities.
- Regulatory shifts in electrical safety and emissions — new standards can create short-run compliance costs and long-run market advantage for early adopters.
- Construction and industrial activity indices — demand sensitivity remains highest to capex and renovation cycles.
- Channel inventory and sell-through rates — divergence between distributor inventories and point-of-sale can signal pending price competition or supply constraints.
- Consolidation activity among mid-tier suppliers — rapid roll-ups can change supplier bargaining power overnight.
How PW Consulting can accelerate your 2026 agenda
PW Consulting couples deep industry bench strength with hands-on commercial execution. If you engage with us, we will:
- Deliver a compact executive dashboard (KPIs and triggers) tailored to your product portfolio and markets of interest.
- Run a rapid commercial due diligence stream for M&A targets, with integration playbooks and 100-day value-capture plans.
- Co-create product and channel pilots that test cordless, service-based, and premium-performance propositions in controlled geographies.
- Provide workshop-based alignment with sales, product, and operations to translate market scenarios into 2026 budgets and R&D roadmaps.
Next steps — why the full report matters
This brief highlights the strategic vectors that will shape success in 2026. To act with conviction, you need the full set of granular inputs that inform investment sizing, SKU-level pricing, and regional go-to-market sequencing. While this introduction surfaces the market’s trajectory, concentration dynamics, and practical implications for corporate strategy, the detailed subsegment datasets (by type, application, and region), supplier lists, and modeled scenarios are intentionally withheld here to preserve actionable exclusivity in the full PW Consulting deliverable.
For leaders who must translate a 4.3% forecast CAGR and a structurally consolidating landscape into profitable action: secure the full report, adopt a prioritized execution plan, and treat 2026 as the year to convert product and channel investments into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Heat Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copper Sulfate Pentahydrate Market to Hit USD 576.8M by 2032 (5.4% CAGR)
By pmarketresearch, 2026-07-30
Copper Sulfate Pentahydrate Market: Strategic Intelligence for 2026 Decision-Making
Executive trailer
As companies realign supply chains and product portfolios for the post‑pandemic and decarbonization eras, Copper Sulfate Pentahydrate emerges as a quietly critical intermediate across agriculture, feed, electroplating and specialty industrial applications. This PW Consulting briefing introduces our full Copper Sulfate Pentahydrate Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) and explains why the insights it contains are indispensable for boardrooms and procurement teams planning for 2026.
Copper Sulfate Pentahydrate Market
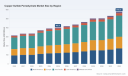
Key macro position: the global market, measured in USD Million, expanded from approximately 315.2 in 2020 to 402.5 in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.4% through 2032 — reaching an estimated 576.8 by 2032. These topline dynamics reflect the combined effects of agricultural demand resilience, selective industrial recovery, and periodic supply shocks that amplify volatility in certain grades.
Copper Sulfate Pentahydrate Market
Why this report matters for 2026 strategy
-
Operational resilience: the market’s steady mid‑single‑digit CAGR masks episodic supply and quality disruptions that can rapidly cascade into production stoppages or costly recalls. Companies that treat copper sulfate as a strategic raw material — not a commoditized, low‑touch buy — will avoid expensive remediation.
Copper Sulfate Pentahydrate Market -
Regulatory and reputational risk: recent regulatory activity (notably a voluntary recall in April 2026 of contaminated feed‑grade lots originating from China) underscores the need for traceability, batch testing, and contract clauses that allocate recall costs. The recall and confirming reports of dioxin contamination have already prompted faster adoption of upstream verification protocols among North American and European buyers.
-
Commercial differentiation: as customers demand higher‑assurance materials (GMP/USP/FCC/technical certificates, documented supply chains, and product stewardship), producers with certified quality systems and transparent traceability can capture premium pricing and longer contracts.
-
M&A and vertical plays: the market’s structure and pockets of regional specialization create tactical opportunities for acquisitive buyers to secure high‑purity feeds, backward integrate into feed‑grade production, or establish regional hubs that reduce lead times and import risk.
What the full report delivers (practical, transaction‑ready content)
-
Robust market sizing and forecast model (USD Million; 2020–2032) with build‑up logic and sensitivity toggles to test price, feedstock availability and regulatory stress scenarios.
-
Demand driver diagnostics by grade and application, with elasticities and scenario impacts (presented qualitatively in this preview; granular subsegment volumes and shares are reserved for the full report to maintain competitive value).
-
Supply map and capacity registry covering global producers, conversion facilities, and logistical chokepoints; includes lead‑time benchmarks and alternative routing playbooks for emergency sourcing.
-
Supplier due‑diligence toolkit: audit checklists, required certificate templates, in‑market testing regimes and contract language to mitigate contamination risk and supplier non‑performance.
-
Price build and trade dynamics: raw‑material drivers, pass‑through analysis, and a proprietary pricing deck for use in negotiation and budgeting.
-
Regulatory tracker and recall playbook: mapping of current controls across major markets, recall impact scenarios, insurance considerations and crisis communication templates.
-
Competitive landscape intelligence: profiles and strategic positioning of key players, capability matrices, and a short list of potential targets and partners for buyers and investors.
-
Actionable growth roadmaps: go‑to‑market plays, cost‑to‑serve optimization, and a prioritized list of tactical initiatives with expected ROI and implementation timelines for 6–24 months.
High‑level competitive landscape and strategic implications
The Copper Sulfate Pentahydrate market sits in a middle ground of specialization: several established producers serve distinct channels (pharma/nutraceutical, agricultural, feed, electroplating, and industrial uses), while many smaller suppliers address local commodity demand. The market is best characterized as moderately fragmented: the largest regional players collectively do not exert dominant, global pricing control, leaving room for consolidation and margin capture through quality differentiation and logistics efficiency.
-
Shreeji Industries (India) — GMP‑certified manufacturer supplying IP/BP/USP/FCC grades. Strengths: pharmaceutical‑grade credentials, multi‑grade capability and a clear focus on higher‑value channels (nutraceuticals, fungicides, electroplating). Strategic implication: potential partner or acquisition target for firms seeking a certified, Asia‑based, quality‑assured source and faster entry into regulated markets.
-
Sulfozyme Agro India Pvt Ltd (India) — supplier oriented to agricultural and technical grades for plant nutrition, fungicide formulations and feed additives. Strengths: proximity to large agricultural demand pools, specialized technical grade production. Strategic implication: attractive for agricultural chemical formulators that require integrated supply and formulation co‑development; also a candidate for off‑taker agreements or joint quality uplift programs.
-
Univerical (United States) — North American manufacturer of high‑purity liquid and crystalline products for electroplating and industrial uses. Strengths: regional manufacturing, focus on high‑purity and plating‑on‑plastics niches, shorter lead times for North American customers. Strategic implication: natural partner for Western buyers seeking to reduce import dependency and to secure more consistent quality for industrial applications.
Each player illustrates a strategic axis buyers should evaluate: quality certification (GMP/USP/FCC), geographic risk (local production vs. import dependence), and channel focus (agriculture/feed vs. electroplating/industrial). The full report contains head‑to‑head capability matrices and supplier scorecards that buyers can use immediately in sourcing decisions.
Supply‑chain vulnerability spotlight — the 2026 contamination episode
April 2026 saw a voluntary recall of contaminated feed‑grade Copper (II) Sulfate Pentahydrate lots originating from China, reported by the Animal Nutrition Association of Canada and flagged by national food safety authorities. The contamination—associated with dioxin residues—has tangible operational implications:
-
Immediate testing and batch hold policies are now business‑critical for feed and agricultural formulators selling into regulated markets.
-
Buyers must reassess audit frequency, third‑party lab validation, and contractual warranties to allocate recall and remediation costs.
-
Regionalization of supply (or strategic inventory buffers) may be justified despite added holding costs for customers with zero‑tolerance product profiles.
The PW report contains a forensic appendix on the recall, a recommended lab‑testing protocol, and a supplier‑risk matrix that quantifies expected disruption costs under multiple contamination scenarios.
Strategic recommendations for leadership teams planning in 2026
-
Procurement: shift from single‑source spot buys toward blended buying strategies: certified regional suppliers for critical applications and vetted global suppliers for cost flexibility. Implement mandatory incoming batch testing for feed and pharma grades.
-
Quality & Regulatory: prioritize suppliers with third‑party certifications and documented chain‑of‑custody. Insert contractual clauses for recall liability, and secure contingent supply agreements with tested alternates.
-
Operations: evaluate regional buffer stocks and near‑shoring for high‑assurance grades. Rebalance safety stock vs. working capital to reflect the realized risk premium post‑recall.
-
Commercial & R&D: explore premiumization for traceable, certified grades and invest in formulation changes that reduce copper sulfate dependence where possible (or increase recrystallization/upgrade steps to capture margin).
-
M&A & Partnerships: screen targets that provide quality uplift, regional manufacturing, or access to regulated markets. Consider minority investments in certified producers to secure preferential supply.
-
Risk & Finance: stress‑test budgets with the PW forecast scenarios (base, supply shock, regulatory tightening) and ensure insurance coverage aligns with identified recall exposure.
How to use this briefing and next steps
This article is a focused executive preview designed to communicate the strategic value embedded in our full market study. For procurement teams, the buyer’s toolkit and supplier scorecards are immediately actionable. For corporate strategy and M&A teams, the sector mapping and candidate shortlists accelerate diligence. For R&D and product teams, the formulation impact assessments spotlight opportunities to reduce raw material intensity or develop premium, differentiated product lines.
The complete PW Copper Sulfate Pentahydrate Market report contains the granular sub‑segment volumes, regional and application splits, price decks, full company profiles and the quantitative scenario models that underpin the recommendations summarized above. Those detailed elements are intentionally held in the full report to preserve competitive advantage — and they are precisely what your commercial and sourcing teams will need to operationalize 2026 plans.
Call to action
To obtain the full dataset, supplier scorecards, risk matrices and the downloadable forecast model (2026–2032), visit our report page or contact PW Consulting’s industry team. If you are preparing 2026 budgets, negotiating multi‑year offtake agreements, or evaluating acquisition targets, securing the complete intelligence now will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Copper Sulfate Pentahydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gibberellin Acid Market Poised for 8.15% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-30
Gibberellin Acid (GA) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary: why this briefing matters for 2026 strategy
As companies reset budgets and strategic priorities for 2026, plant growth regulators — and gibberellin acids (GAs) in particular — have moved from niche tool to an operational lever across fruit production, specialty crops, malting and turf management. Our market modelling shows a clearly accelerating revenue trajectory from a 2025 base to 2032, underpinned by sustained demand for yield/quality improvement, regulatory reclassifications, and manufacturing innovation. The market, measured in USD Million, grew through 2020–2025 and, with a compound annual growth rate of 8.15% over the forecast window, reaches materially higher absolute scale by 2032.
Gibberellin Acid (GA) Market
For executives evaluating portfolio allocation, M&A, commercial expansion or manufacturing investments in 2026, this report functions as both a decision support tool and a competitive intelligence compass: it validates the commercial opportunity in headline metrics while reserving the granular, actionable segment tables and price-volume curves for licensed subscribers.
Gibberellin Acid (GA) Market
Market trajectory at a glance (base year and forecast)
- Base year: 2025 (established as our anchor for model calibration)
- Forecast horizon: 2026–2032
- Compound annual growth rate (CAGR): 8.15% across the forecast period
- Our bottom-line view: the GA industry transitions from steady supplementation to strategic crop-management adoption, with 2026 representing the inflection year when product innovation and regulatory clarity converge to expand commercial pathways.
To give executives a sense of scale without substituting for contract-level market data: the modelled market expands meaningfully year-on-year from the 2025 anchor into the 2026–2032 window, reflecting both volume-driven adoption and value accrual from higher-margin formulation innovations. Our financial modelling is denominated in USD Million and supports scenario analysis at range-bound, base-case and upside assumptions — all available in the full report.
Gibberellin Acid (GA) Market
Key dynamics shaping the GA market in 2026
- Regulatory clarity and re-registration cycles. Recent regulatory activity at both regional and federal levels has reduced compliance uncertainty. Notable administrative updates and renewal processes in 2025–2026 have created predictable windows for formulators and registrants to secure or expand labeled uses. Firms with regulatory bandwidth can convert this predictability into faster label extensions and broader crop claims in 2026.
- Product innovation pushes premiumization. The market is seeing formulation-led differentiation — lower-volatility concentrates, organic-eligible registrations and crop-specific blends that unlock new use-cases (e.g., delayed ripening, shelf-life extension, cell expansion). Recent product introductions demonstrate the willingness of large agri-players to seek higher-margin, value-added PGR offerings.
- Manufacturing and input-cost evolution. Advances in fermentation and bioprocessing — including probiotic-enabled fermentations and other optimized bioproduction techniques adopted late in 2025 — have improved unit economics across the supply chain. This both compresses cost for bulk suppliers and permits reinvestment in formulation R&D for differentiated products.
- Commercialization and channel sophistication. Adoption is being driven not only by price and efficacy but by better integration into agronomic service models, supply-chain partnerships with packers/processors, and digital agronomy that quantifies GA impact on post-harvest value. Companies that treat GA products as a service — combining application timing, analytics and crop-rotation playbooks — will capture disproportionate share of value.
- Market structure and concentration. The competitive landscape is moderately fragmented: aggregate concentration metrics highlight that the top three to five players do not dominate to the degree seen in other agrochemical segments. This structural openness creates opportunity for fast-followers and specialists to scale via targeted shelf-space, channel partnerships and formulation niches.
Competitive landscape — how leading players are positioning (implications for partners and rivals)
The GA market combines legacy agrochemical incumbents, specialty formulators, and large regional producers. Key actors illustrate distinct strategic archetypes:
- Platform incumbents focused on brand & channel (example: Valent BioSciences, Nufarm, Corteva). These players leverage established distribution networks, registered labels, and brand trust to commercialize full-channel rollouts. Their advantage lies in integrated marketing to growers and in regulatory resources to expand labeled uses. Expect these firms to prioritize high-visibility crop segments and formulations with clear ROI stories.
- Specialty formulators and turf/aquatic specialists (example: Fine Americas, SePRO, Greenleaf Chemical). These companies compete on tailored formulations and technical support for horticulture, ornamentals and turf. They are natural partners for packers and nursery chains seeking customized dosing and application timing.
- Cost-competitive bulk producers (example: Jiangsu Fengyuan, Zhengzhou Delong). Producers with scale in bulk GA synthesis or fermentation can underwrite competitive pricing and supply reliability. Their strategic path is either to remain B2B suppliers to formulators or to pursue forward integration into branded lines where channel access exists.
- New product entrants and organic-eligible offerings (example: Corteva's recent launch). Companies launching low-volatile, organic-eligible formulations are targeting premium segments and sustainability-focused customers. These launches signal that regulator-approved, market-differentiated GA products can command higher price points and may catalyze adoption in crops previously unconvinced by conventional formulations.
For 2026, strategic actions by competitors will cluster around three playbooks: (1) accelerate label expansion and OMRI/organic clearances; (2) scale margin-enhancing formulations and service bundles; (3) secure raw-material sourcing via long-term supply agreements or backward integration. Firms pursuing multiple tracks simultaneously will require careful capital allocation and disciplined go-to-market sequencing.
Where the commercial opportunities lie — pragmatic scenarios for 2026
- Premiumization in high-value fruit and specialty crops. Grower willingness to pay increments for quality and shelf-life improvements creates an attractive avenue for higher-margin formulations. Sales teams should refocus on packer contracts and post-harvest service propositions.
- Service-led adoption in malting and industrial crops. In segmented, process-sensitive applications, integrating product application with agronomic advisory services reduces user hesitation and locks in annuity revenues.
- Channel rollups and co-pack agreements. Distributors and regional formulators can secure supply and margins by signing multi-year supply or co-manufacturing deals with bulk producers — an effective hedge against short-term price volatility.
- Regulatory arbitrage through targeted registrations. Prioritize territories and label claims where the regulatory timeline offers first-mover advantage in 2026–2027.
What the full report contains — practical deliverables for strategy teams
Our full Gibberellin Acid Market study is structured for operational use by commercial, regulatory, and M&A teams. It includes:
- Detailed historical and forecast revenue series (2020–2032) denominated in USD Million, with scenario sensitivity and unit-volume drivers;
- Segment-level demand drivers, pricing dynamics and margin matrices (note: granular segment tables and proprietary share estimates are gated for subscribers);
- Regulatory matrix and timeline by jurisdiction, highlighting re-registration windows, label extension pathways and compliance cost estimates;
- Supplier and channel maps with risk heatmaps for raw-material concentration, logistics exposure and single-source dependencies;
- Commercial playbooks — go-to-market frameworks for branded formulations, service bundles, and contract manufacturing partnerships;
- Due-diligence checklist and valuation heuristics for potential M&A targets in bulk, formulation, and channel assets;
- Appendix of primary and secondary sources, including recent product launches and regulatory notices for 2025–2026.
How to use the insights in 2026 planning cycles
- Board level: Use our scenario outputs to stress-test capex asks tied to new formulation lines or fermentation capacity, and to inform M&A premium tolerance for strategic acquisitions.
- Commercial leaders: Revisit channel incentives and pricing tiers using the report’s margin ladder and breakeven timelines; prioritize crops and packer relationships where shelf-life premiumization creates the sharpest ROI.
- R&D and registration teams: Align pipeline priorities with regulatory windows and product features that unlock premium status (e.g., low-volatility, organic-eligible formulations).
- Supply chain and procurement: Reconfigure supply agreements to insulate against feedstock volatility and to capture benefits from improved bioprocess economics.
Closing — the strategic playbook for 2026
Gibberellin acids are no longer a specialist curiosity: they are a strategic lever in crop-value engineering. Our modelling — anchored on a 2025 base year and projecting forward to 2032 at a compound annual growth rate of 8.15% — shows a market that rewards both operational excellence in production and commercial sophistication in go-to-market. The competitive field is sufficiently open that disciplined entrants can capture share, but success in 2026 will be decided by three capabilities: regulatory execution, formulation differentiation, and integration into customer value chains.
This article is a high-level preview of the analytical depth available in PW Consulting’s full Gibberellin Acid (GA) Market report. To review the complete segment matrices, proprietary share estimates, and ready-to-execute playbooks that support board-level decisions in 2026, please consult the full study on our website.
For detailed analysis of this topic, please visit the official page: Gibberellin Acid (GA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Rubber market to hit USD 344.8M by 2032 at 5.86% CAGR
By pmarketresearch, 2026-07-30
Natural Rubber Market 2026: Strategic Outlook and Decision-Grade Insights
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our 2026 Natural Rubber Market study. This briefing synthesizes the authoritative market sizing, trajectory and strategic implications that corporate leaders, procurement heads and investors need to act with confidence in 2026 — while preserving the granular, transaction-grade datasets for readers who access the full report.
Natural Rubber Market
Executive snapshot
The natural rubber market has demonstrated steady recovery and expansion through the 2020–2025 historical window, with our base year set at 2025. Measured in USD (Million), total market revenue moved from an earlier cycle low to an elevated 2025 level and — under our central forecast path — is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of approximately 5.86%. By 2032 the market reaches a materially larger scale, reflecting demand resilience in key applications and structural supply dynamics that will shape strategic choices in 2026.
Natural Rubber Market
Why this study matters for 2026 decision-making
- Actionable foresight: The report translates macro growth (2020–2025 history and a 2026–2032 forecast horizon) into tactical signals for procurement windows, contract tenors and inventory policy. It identifies time-sensitive inflection points where supply constraints and regulatory milestones converge.
- Risk-to-return mapping: We connect physical supply risks, commodity price drivers and evolving sustainability rules to quantify downside exposure for manufacturers and traders — enabling calibrated capital allocation and hedging strategies.
- Competitive advantage: The study surfaces strategic levers for producers and processors — from traceability investments and upstream partnerships to premium product positioning — that can convert regulatory compliance into price differentiation and margin capture.
Market trajectory and underlying drivers
The market’s recent expansion is neither accidental nor uniformly distributed: structural demand from mobility and industrial rubber goods plus cyclical restocking drove the recovery through 2025. Our forecast to 2032 assumes continued urbanization, vehicle parc growth in emerging markets and a shift in product mixes toward higher-value latex and specialty grades. On the supply side, natural rubber’s biological production cycles, land-use constraints and climate variability create a baseline of limited elasticity — meaning supply shocks propagate quickly into availability and commercial terms.
Natural Rubber Market
Key drivers that executives must monitor in 2026 include:
- Regulatory compliance costs and traceability requirements that raise the marginal cost of sourcing from opaque supply chains.
- Climate and weather risk affecting core producing regions and smallholder yields, which can compress supply in short windows.
- Downstream substitution and product innovation trends (e.g., synthetic blends, engineered elastomers) that alter premium spreads and long-term demand composition.
Regulatory inflection: EUDR and the new compliance horizon
Regulatory changes in 2026 create a firm, date-certain obligation for market participants interacting with the EU: supply-chain traceability and no-deforestation evidence will be mandatory for natural rubber and rubber-based products placed on the EU market. This is not a distant policy risk — it is a near-term operational reality that impacts onboarding, certification timelines and supplier qualification. Large operators should assume immediate resource needs for plot-level traceability, third-party verification pathways and supplier engagement protocols.
Supply dynamics and the short-term shock layer
Beyond structural constraints, the market’s short-term risk profile has been elevated by episodic production disruptions. Recent extreme-weather episodes in key producing geographies have tightened available volumes and exposed the limits of spot-market flexibility. For 2026 planning, commercial teams must treat weather-related production disruptions as persistent tail risks and stress-test supply scenarios across a range of durations and intensities.
Competitive landscape — what the market structure implies
The natural rubber processing and exporting segment is dominated by several integrated, vertically proficient players that combine plantation exposure, processing scale and global trading networks. These firms — ranging from large Thai processors to Malaysia- and Vietnam-based integrated groups — set commercial norms for quality specification, service levels and traceability capabilities. For buyers, this concentration translates into a twofold strategic reality:
- Counterparty stability: long-term contracts with established processors can reduce volatility in physical availability and support traceable sourcing commitments.
- Supplier power: concentrated processing capacity gives leading processors leverage to enforce premium structures for certified, compliant material and to set delivery terms during constrained periods.
Our full study profiles the leading processors and exporters in depth, assessing their asset footprints, sustainability programs and supply-chain reach. We identify which players are positioned to meet traceability requirements and which may face capital or operational constraints as compliance timelines accelerate.
What practical, operable content the full report contains
- Methodology and assumptions: base year (2025), historical window (2020–2025), forecast horizon (2026–2032), currency and units, and sensitivity scenarios around price and supply shocks.
- Top-line market sizing and growth trajectory, with scenario-based forecasts under alternative demand and supply pathways.
- Supply-chain mapping and risk heatmaps that identify geographic, operational and governance exposures at each node of the value chain.
- Regulatory impact assessment: compliance playbooks for EUDR readiness, auditability pathways and supplier engagement templates.
- Commercial playbook: procurement tactics, contract structures, inventory optimization heuristics and hedging instruments calibrated to rubber market behavior.
- Competitive benchmarking: executive summaries of major processors and suppliers, their strategic strengths and gaps, and M&A/partnership opportunities.
- Executive dashboards and data annexes: downloadable tables, forecast series and scenario outputs suitable for board-level briefings and procurement systems.
Practical strategic recommendations for 2026
Based on our integrated analysis, we recommend that market participants prioritize the following actions in 2026:
- Operationalize traceability now: invest in plot-level traceability pilots with a subset of suppliers and align contractual terms to on-ramp compliance documentation. Delay increases implementation risk and cost.
- Diversify sourcing across supplier archetypes: combine relationships with integrated processors, regional aggregators and certified smallholder cooperatives to balance cost, traceability and resilience.
- Adopt a layered procurement approach: blend short-term spot purchases (for flexibility) with multi-year supply agreements tied to sustainability milestones and index-linked pricing.
- Invest in supplier capacity building: co-fund yield-improvement and sustainability programs with trusted suppliers to reduce future compliance costs and secure preferential access to certified volumes.
- Prepare contingency capital: maintain liquidity buffers and pre-arranged credit lines to act quickly when physical availability tightens and premiums emerge.
- Assess strategic M&A and alliance targets: prioritize assets that provide traceable supply, processing control or technological capability (e.g., traceability platforms, analytics providers) that can be integrated within 12–18 months.
Implications for investors and financial sponsors
The market’s mid-term growth path and concentrated processing base create selective investment opportunities. Value capture will favor firms that can credibly de-risk supply chains against regulatory and climate shocks, demonstrate premium product differentiation and scale traceability economically. Our report surfaces targets and partnership models that can de-risk buyer portfolios and accelerate revenue capture in certified product lines.
Why this is a ‘trailer’ not the full movie
This article is intended to surface the strategic contours you need to act in 2026 — the full report contains the granular segmentation, regional allocation, application-level demand detail and downloadable time-series data you will require to operationalize the recommendations. We deliberately withhold the transaction-level tables and subsegment percentages here so that decision-makers can access the validated datasets through the report portal and apply them directly to commercial models, risk systems and board materials.
Next steps
- Procurement and supply-chain leaders should request our compliance playbook to begin traceability pilots this quarter.
- Strategy and corporate development teams should book a briefing to review our supplier scorecards and prioritized M&A targets.
- Investors and traders: contact PW Consulting for the full forecast tables, scenario outputs and bespoke valuation overlays.
PW Consulting’s Natural Rubber Market report is built to be a practical tool for 2026: rigorous in method, targeted in recommendations and executable at commercial scale. For the full datasets, segment-level analysis and proprietary company benchmarking that underpin these conclusions, please access the complete report on our website or contact our team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Natural Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radiopharmaceuticals Market to Hit USD 10.56 Billion by 2032
By pmarketresearch, 2026-07-30
Radiopharmaceuticals Market 2026: A Strategic Preview for Executive Decision-Making
Between 2020 and 2025 the radiopharmaceuticals market moved from an emerging niche to a commercially material sector—growing from approximately USD 3.5 billion to roughly USD 6.0 billion. Our base year for the full study is 2025, and the forecast horizon extends 2026–2032. Over that forecast period the market is modeled to expand at a compound annual growth rate (CAGR) of about 8.5%, reaching an anticipated total north of USD 10 billion by 2032. That trajectory, combined with a moderate industry concentration (top-three and top-five firms representing meaningful but non‑dominant shares), creates opportunity and complexity for life‑science CEOs, CDMO leaders, investors and hospital systems planning capital allocation in 2026.
Radiopharmaceuticals Market
Why this study matters for 2026 corporate strategy
2026 will be a pivotal planning year. Three convergent forces—accelerating therapeutic innovation, supply‑side capacity constraints for critical isotopes, and shifting public policy on domestic production and trade—will materially influence commercial outcomes over the next three to seven years. Our report translates these forces into actionable intelligence by combining a rigorous market-size baseline (2020–2025), scenario-driven forecasts (2026–2032), and company‑level playbooks. For executive teams, the strategic value is practical: prioritize capital projects and partnerships that preserve launch timetables for novel radiotherapies, mitigate tariff and reimbursement risk, and position supply chains to capture the higher‑margin therapeutic opportunity as it matures.
Radiopharmaceuticals Market
What the numbers tell you (and what we deliberately withhold)
- Macro growth is real and sustained: from ~USD 3.5B in 2020 to ~USD 6.0B in 2025, with a modeled rise toward ~USD 10.56B by 2032 at an 8.5% CAGR for 2026–2032.
- Concentration is meaningful without being prohibitive: incumbent producers and vertically integrated players hold strong positions, yet the market leaves room for CDMOs, specialized isotope suppliers and therapeutic innovators.
- We intentionally do not publish granular segment shares or regional breakdowns in this preview. Those strategic detail layers—regional and application splits, pricing curves and contract‑level margins—are core deliverables in the full report and are the levers you will need to finalize 2026 capex and M&A decisions.
Competitive landscape: the players you must model into your scenarios
Across the value chain you will find three archetypes: vertically integrated isotope producers and radiopharma originators, specialist contract development and manufacturing organizations (CDMOs), and focused therapeutic developers. The competitive set we model in depth includes established producers and faster-scaling CDMOs, each with different strategic implications:
Radiopharmaceuticals Market
- Telix Pharmaceuticals (Melbourne): expanding GMP capacity in Europe and Asia, with operational manufacturing sites deployed to support commercial diagnostic and therapeutic supply—these assets change supply availability and contract negotiation dynamics in 2026 and beyond.
- ITM Isotope Technologies Munich SE (Garching): a vertically integrated company with leadership in accelerator and isotope production pathways; their portfolio and production posture are a strategic hedge for sponsors seeking assured access to certain therapeutic isotopes.
- Nucleus RadioPharma (Rochester) and Evergreen Theragnostics (Springfield): US‑based full‑service CDMOs offering end‑to‑end development and manufacturing—critical partners for sponsors aiming to accelerate clinical development without investing in in‑house manufacturing.
- PanTera (Mol) and specialized developers such as RayzeBio and Perspective Therapeutics: players focused on advanced alpha and beta emitter precursors and finished therapies—their progress on Ac‑225 and Lu‑177 pathways is a key variable in therapeutic adoption curves.
- Cardinal Health: represents the distribution and logistics layer that becomes increasingly strategic as therapy administration settings diversify and supply‑chain traceability rises in importance.
The full report contains proprietary supplier maps, capability matrices and a five‑node risk scoring model (technical, regulatory, geopolitical, commercial and logistics) for each of these organizations. In the preview we demonstrate posture and momentum—while reserving the contract-level benchmarking and supplier scorecards for report subscribers.
Recent developments shaping tactical choices in 2026
- Facility moves and capacity: Multiple announcements through 2025–2026 indicate an industry in capacity expansion mode—new research and GMP facilities coming online, and permitting progress for dedicated Ac‑225 production. These are inflection points for sponsors needing guaranteed supply windows.
- Technology partnerships for novel isotopes: Collaborative projects to develop next‑generation isotopes (e.g., photonuclear routes, Astatine programs) will determine who secures first-mover advantage in next‑wave alpha therapies.
- Trade and tariff risk: Recent governmental proclamations announced in early 2026 introduce potential ad valorem duties and phased tariff schedules for imported pharmaceuticals and inputs—an operational and P&L risk that must be stress‑tested in 2026 budgeting cycles.
- Regulatory and reimbursement updates: New guidance on oncology radiopharmaceutical dosage optimization and CMS payment adjustments for domestically produced doses change the economic calculus for local manufacturing investments and pricing strategies.
Regulation, reimbursement and the domestic production premium
Two policy changes merit elevated attention. First, payors and regulators are beginning to explicitly reward domestic production—CMS introduced add‑on payments for certain domestically produced study doses and maintained cost‑based methodologies for separately payable diagnostic radiopharmaceuticals. Second, the FDA’s draft guidance on dosage optimization for oncology radiopharmaceuticals signals heightened expectations around clinical development pathways, PK/PD modeling and manufacturing consistency. Together, these changes make a strong case for sponsors to model a 'domestic production premium' in price sensitivity and to prioritize clinical packages that address optimized dosing from Phase II onward.
Supply chain realities and isotope scarcity
Long lead times for new irradiation and processing capacity, coupled with surging demand for isotopes such as Lu‑177 and Ac‑225, create persistent supply risk. The market is not purely demand‑driven: bottlenecks in production scale can impose launch delays, increase unit costs, and shift bargaining power toward suppliers with vertically integrated isotope ecosystems. Our report uses a factory‑level build‑out timeline model and isotope availability scenarios to quantify the expected degree and timing of constrained supply under multiple adoption curves.
What the full PW Consulting report delivers (operationally focused)
- Validated market-sizing and forecast framework: back‑tested against 2020–2025 performance with transparent assumptions for 2026–2032 scenarios.
- Commercial sensitivity analyses: price and reimbursement shock models, tariff stress tests, and domestic vs. import supply-case P&L impacts.
- Supplier and capability maps: audited GMP assets, isotope production capacity timelines, and CDMO lead times—presented with a supplier risk score per node.
- Regulatory impact matrix: mapping new FDA guidance, CMS payment updates and tariff proclamations to clinical development milestones and commercialization costs.
- M&A and partnership heatmaps: targets and rationale for bolt‑on CDMOs, upstream isotope plays, and late‑stage therapy licenses—ranked by strategic fit and time‑to‑value.
- Executive playbook: 12‑month and 36‑month action plans tailored to three archetypes (Sponsor, CDMO, Distributor) with decision triggers and investment thresholds.
Immediate strategic recommendations for 2026 planning
- Model tariff and reimbursement sensitivity into every scenario. Build worst‑case duty and delayed‑launch assumptions into capex and licensing schedules to avoid negative surprises.
- Secure multi‑tiered supply agreements with clear force‑majeure and capacity allocation clauses. Given isotope scarcity, prioritize contractual certainty over marginal price concessions.
- Prioritize modular, scalable manufacturing investments (e.g., cleanrooms and cyclotron capacity) that accelerate time‑to‑clinic while limiting stranded asset risk.
- Use the FDA draft guidance to pre‑emptively refine dosing strategies; better early optimization reduces costly late‑stage rework and supports stronger reimbursement positioning.
- Assess opportunistic M&A: target CDMOs with validated GMP track records or niche isotope producers with near‑term capacity declarations to shorten supply risk horizons.
How to use this preview
This article is a strategic primer: it surfaces the macro trajectory and the practical forces executives must factor into 2026 decisions, while preserving the granular, supplier‑level intelligence that drives transactional moves. If your 2026 plan includes capital projects, manufacturing partnerships, or late‑stage licensing in radiopharmaceuticals, the full PW Consulting study supplies the regionally and segment‑specific data, supplier scorecards, and contract‑level margin benchmarking you will need to finalize commitments.
In an industry where isotope availability, regulatory nuance and policy shifts can compress or extend commercial runways overnight, decision makers who blend scenario discipline with supplier certainty will win. Our research is designed to move your strategy from assumptions to defensible decisions—fast.
For detailed analysis of this topic, please visit the official page: Radiopharmaceuticals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Physiological Saline Market to Reach USD 8.8B by 2032 at 7.4% CAGR
By pmarketresearch, 2026-07-30
Physiological Saline Market — Strategic Preview for 2026 Decision-Making
As health systems stabilize after recent supply shocks and as clinicians and procurement teams recalibrate sourcing strategies, physiological saline remains one of the most strategically important commodities in acute care and ambulatory settings. PW Consulting’s forthcoming market research, based on a 2025 base year and a 2026–2032 forecast horizon, synthesizes five years of historical performance (2020–2025) and projects forward under multiple scenario assumptions. At the macro level, the market is projected to expand at a compound annual growth rate (CAGR) of 7.4% from 2026 through 2032, progressing from an estimated USD 5,200 Million in 2025 to roughly USD 8,800 Million by 2032. This briefing previews the strategic intelligence in the full report and highlights the direct actions executives should be prioritizing in 2026.
Physiological Saline Market
Why this market matters in 2026
-
Operational leverage: Physiological saline is both a high-volume clinical input and a gateway product that shapes hospital procurement relationships, IV therapy formularies, and supplier contracting cycles.
Physiological Saline Market -
Margin and mix dynamics: While saline itself is a low-margin, high-volume item, packaging formats, proprietary container technologies, and supply reliability create differentiated value capture opportunities.
Physiological Saline Market -
Systemic risk mitigation: The industry’s recovery from prior shortages and the regulatory actions that followed mean supply-chain resilience now influences capital allocation and partnership strategies across hospital systems and manufacturers.
Market snapshot: growth trajectory and structural drivers
From a historical base of approximately USD 3,500 Million in 2020, the global physiological saline market experienced steady recovery and acceleration through 2025, driven by expanded elective care, increased outpatient hydration and infusion therapy utilization, and stabilization of manufacturing capacity. The market scale reached an estimated USD 5,200 Million in 2025. Under PW Consulting’s central forecast—reflecting demand normalization, moderate price pressure, and investment in non-PVC packaging—the market is expected to grow to about USD 5,464 Million in 2026 and to roughly USD 8,800 Million by 2032, representing a 7.4% CAGR over the forecast period. These headline figures underscore a resilient, mid-single-digit-to-low-double-digit growth market that rewards both scale and operational excellence.
What the report contains (practical, action-ready intelligence)
-
Executive dashboards: Clear KPIs for procurement, manufacturing, and commercial leaders—capacity utilization thresholds, reorder point frameworks, and packaging ROI models tailored for 2026 procurement cycles.
-
Demand modeling: Scenario-based demand curves that incorporate clinical utilization trends, outpatient infusion expansion, and potential episodic demand shocks—presented with sensitivity analyses to inform buffer-stock policies.
-
Supply map and risk heatmap: Granular supplier mapping, contract tenure analysis, and geographic fragility indices to guide near-term dual-sourcing or stockpiling decisions.
-
Commercial playbooks: Tender-winning approaches by region and channel, value-based contracting constructs for hospital networks, and pricing levers informed by reimbursement code dynamics.
-
Manufacturing and packaging assessment: Capex prioritization matrix for converters and OEMs, cost trade-offs between PVC vs. non-PVC containers, and guidance on lifecycle management of sterile fill lines.
-
M&A and partnership screening: Criteria-driven targets for bolt-on manufacturing capacity, regional distribution partnerships, and technology licensing opportunities.
-
Regulatory and reimbursement tracker: Up-to-date mapping of critical codes, policy changes, and shortage declarations that materially affect unit economics and procurement negotiation posture.
Competitive landscape: what leading firms are doing
The physiological saline market remains strategically contested by a set of established injectable and IV-fluid specialists. Leading manufacturers emphasize reliability, container innovation, and integrated hospital solutions rather than volume-only competition. Key strategic positions observed in the market include:
-
Baxter International: A long-standing leader in IV fluids, Baxter’s Viaflex and Viaflo systems continue to anchor hospital procurement lists. Recent commercial expansion initiatives in early 2026 indicate a push to broaden market access and reinforce supply commitments—moves that increase competitive pressure in markets where buyers prioritize single-supplier simplicity and validated logistics.
-
B. Braun Melsungen: With a portfolio built around extracellular fluid replacement in established container formats, B. Braun pursues a steady combination of clinical education and channel depth to defend share in hospital formularies where clinical familiarity and product interchangeability matter.
-
Fresenius Kabi: The company’s Freeflex bag strategy and its March 2026 distribution partnership reinforce a distribution-led expansion play. Fresenius is optimizing route-to-market strength to capture growth in markets with fragmented distribution and tender-driven procurement.
-
ICU Medical / Otsuka collaborations: Non-PVC/non-DEHP container offerings and joint manufacturing arrangements reflect a differentiation strategy pitched at hospital systems and procurement teams seeking compliance with emerging patient-safety and sustainability standards.
-
Grifols & Laboratorios Grifols: Positioning around polypropylene bags and plasma-donation applications anchors their relevance in integrated hospital-plasma ecosystems, where cross-selling saline for donation and inpatient use can create channel synergies.
-
Otsuka Pharmaceutical and AdvaCare: These players focus on regional partnerships and branded irrigation/indication-specific products, exploiting agility to serve targeted clinical use-cases and specialized channels.
Across the landscape, the market exhibits a degree of concentration around several incumbent players who control a majority of supply—making scale, validated quality systems, and logistics reliability decisive competitive advantages. The full report provides a deeper assessment of partner fit and competitive risk by scenario; those sub-segment tables and exact share estimates are reserved for the complete study.
Regulatory and reimbursement context shaping 2026 choices
-
Shortage resolution: The FDA formally declared the nationwide shortage of 0.9% sodium chloride injections resolved in August 2025. That regulatory milestone has immediate implications for inventory policies—hospitals that kept elevated safety stocks are now reviewing target levels, and manufacturers are recalibrating production schedules toward optimal utilization rather than emergency surge capacity.
-
Billing and reimbursement: HCPCS code J7030 (infusion normal saline solution, 1000 cc) remains a key billing code; Medicare reimbursement for this code historically averages in a low-single-digit-dollar range per unit depending on setting. Reimbursement nuance continues to affect how providers price outpatient infusion services and how suppliers justify value-added service charges.
-
Infusion service coding: Changes to CPT codes relevant to pre-packaged normal saline fluids (including revisions effective September 2025) affect documentation and reimbursement workflows for hydration services—an operational detail procurement teams must monitor to avoid unfavorable margin shifts in third-party clinic contracts.
Strategic playbook for 2026 — prioritized actions
-
Secure tiered supply: Immediate steps should include establishing multi-year supply agreements with clear capacity guarantees, indexed price collars, and accelerated fulfillment clauses for surge events. Where possible, negotiate inventory consignment or vendor-managed inventory (VMI) to reduce working capital.
-
Invest selectively in packaging: Prioritize conversion to non-PVC containers where clinical or regulatory trends favor them, but adopt a staged approach—pilots in high-volume hospital systems before large-scale capital deployment.
-
Pursue distribution partnerships: For manufacturers seeking market expansion, target partners with tender-execution strength and hospital contracting relationships. Distribution agreements can accelerate adoption without the time-to-market cost of new local manufacturing.
-
Refine commercial models: Align tender bids and private-label propositions with hospital reimbursement realities. For integrated providers, consider bundled care agreements that include infusion services and supply to capture downstream value.
-
Screen M&A targets for resilience and scale: Look for regional production sites with experienced sterile-fill capabilities, plus logistic assets that reduce lead times in priority geographies.
How executives should use this brief and next steps
This preview outlines the strategic imperatives PW Consulting anticipates will most influence decisions in 2026. The full market study contains the granular modeling, supplier scorecards, tender-performance benchmarks, and detailed segment-level estimations necessary to operationalize these recommendations. To protect competitive sensitivity and ensure consultative value, we intentionally withhold sub-segment-level tables and certain regional share breakdowns from this summary; the complete report includes those analytics together with an interactive decision-support toolkit.
If your planning cycle for 2026 encompasses procurement commitments, M&A scoping, or manufacturing investments, we recommend the following immediate next steps: obtain the full PW Consulting Physiological Saline Market report for supplier- and channel-level insight; run a rapid internal sourcing review using our scenario templates; and convene a cross-functional task force (procurement, clinical leads, manufacturing, and finance) to operationalize the priority playbook above.
Closing thought
Physiological saline may read as a commodity on the surface, but its strategic implications in 2026 are far from trivial. The market’s steady growth—anchored by an estimated USD 5.2 Billion base in 2025 and an expected rise to approximately USD 8.8 Billion by 2032 at a 7.4% CAGR—creates opportunities for players who combine scale, supply resiliency, and commercial innovation. PW Consulting’s full report converts these macro trends into executable choices; this preview is designed to orient leadership discussions and highlight where rapid action can lock in advantage in the year ahead.
For detailed analysis of this topic, please visit the official page: Physiological Saline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 1,3-Butylene Glycol Market to Reach USD 321.7M by 2032 at 5.9% CAGR
By pmarketresearch, 2026-07-30
1,3-Butylene Glycol (CAS 107-88-0): Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a focused, decision-oriented preview of our 1,3-butylene glycol market study (base year 2025). The global market has evolved from roughly USD 163 million in 2020 to about USD 212.5 million in 2025, and our modelling projects a confident ascent to more than USD 320 million by 2032 under a compound annual growth rate (CAGR) of approximately 5.9% through the 2026–2032 forecast window. This preview distills actionable implications for strategy teams, corporate development groups, and procurement leaders considering investments, partnerships, or portfolio repositioning in 2026 — while deliberately withholding the granular subsegment tables and regional splits reserved for the full report.
1,3-butylene Glycol (CAS 107-88-0) Market
Why this study matters for 2026
-
Timing: 2026 sits at the inflection between post-pandemic normalization and the next phase of value-chain consolidation. Buyers and sellers will make multi-year commitments this year; accurate midpoint forecasts and risk maps are therefore mission-critical.
1,3-butylene Glycol (CAS 107-88-0) Market -
Scale vs. Specialization: The market’s projected mid-term expansion creates both volume-driven opportunities and premium niches (e.g., bio-derived and pharmaceutical grades) that command differentiated margin dynamics. Our study quantifies these trade-offs and models likely margin impacts under multiple demand scenarios.
1,3-butylene Glycol (CAS 107-88-0) Market -
Regulatory and sustainability thresholds: Certification regimes and regulatory compliance (regional registration frameworks and voluntary ‘clean’ labeling programs) are reshaping procurement specifications and supplier eligibility. The 2026 procurement cycle will reflect these elevated non-price criteria more sharply than previous years.
What the macro picture tells us
The market’s historical trajectory and forecast envelope reveal several high-level truths. After moderate volatility in the early-2020s, the market recovered, with overall revenue moving from the low hundreds of millions (USD) in 2020 to above USD 200 million in 2025. From 2026 onward, the industry demonstrates steady, above-average growth relative to many commodity intermediates, driven by expanding personal care formulations, food-contact applications under stricter safety expectations, and industrial uses that benefit from enhanced supply security.
Importantly, the projected CAGR of about 5.9% across the forecast period reflects a composite of steady baseline demand plus episodic upside from regulatory-driven substitution and bio-based adoption. For executives sizing capacity or evaluating M&A targets, this growth rate is not a signal to expand indiscriminately; rather, it demands calibrated investment that differentiates on feedstock flexibility, certification capabilities, and channel intimacy.
Market dynamics and operational levers
-
Feedstock and route diversification: Two primary production pathways — bio-based fermentation (notably sugarcane-derived routes) and synthetic routes based on petrochemical feedstocks (e.g., butadiene derivatives) — create distinct cost and risk profiles. Supply volatility in hydrocarbon feedstocks can compress margins for synthetic producers, while bio-based routes introduce agricultural exposure (crop yields, sugar pricing) and logistics considerations. Successful players are those who build optionality across routes or secure long-term feedstock arrangements.
-
Regulatory and label-driven demand: Certification frameworks for natural and safer-ingredient claims (e.g., COSMOS, NATRUE, and voluntary labeling schemes recognized by authorities) are accelerating adoption of bio-derived grades in cosmetics and personal care. Simultaneously, regional chemical registration regimes impose compliance costs that influence sourcing strategies — particularly for cross-border suppliers.
-
Concentration and supplier power: The supplier landscape is skewed toward a limited set of capable manufacturers and well-positioned distributors. This structure confers bargaining power to those with scale, proprietary production know-how, or specialized quality certifications. Strategic buyers should expect contracting to favor multi-year frameworks with performance and sustainability clauses rather than spot-only procurement.
-
Certification as a commercial moat: Compliance and certification are increasingly translatable into pricing power. Producers that can demonstrate traceable bio-origin, achieve recognized ‘natural’ seals, or secure high-purity pharmacopeial grades command preferential access to premium channels.
Competitive landscape: who to watch
The competitive set combines global chemical majors, regional producers, and specialized biorefineries. Key players with material strategic relevance include:
-
OXEA GmbH (Oberhausen, Germany) — A well-established supplier offering both industrial and cosmetic grades. OXEA’s integrated supply chains and customer relationships in personal care make it a go-to for formula developers requiring consistency.
-
Daicel Corporation (Osaka, Japan) — Operates at scale with both bio-based and synthetic production routes; recent corporate reviews indicate the company is aligning 1,3-BG activity with broader sustainability and portfolio-efficiency goals.
-
Godavari Biorefineries Ltd. (Hyderabad, India) — A notable bio-derived supplier, leveraging sugarcane fermentation under dedicated branding. Recent throughput optimization efforts highlight the company’s operational focus on meeting certification-driven demand.
-
Penta Manufacturing Company (New York, US) — Offers regulatory-grade variants and focuses on pharmaceutical-intermediate and food-grade applications, an important niche when end-use compliance is a gating factor.
-
Specialist distributors (MMP Inc., Whyte Chemicals, Rita Corporation) — These firms play a critical role in channeling high-purity and compliant product streams into regulated markets, enabling smaller formulators to access certified material without direct manufacturer contracts.
-
Regional producers (Shanghai Jinjin, KH Neochem) — Address localized demand and export flows, especially in high-growth markets across Asia, with competitive cost profiles and tailored grades.
Recent corporate developments reinforce strategic themes for 2026. For example, a 2026 business plan review by a major Japanese manufacturer signals portfolio prioritization and potential rebalancing of capacity allocations. Additionally, announced capacity debottlenecking by a bio-based supplier underscores the near-term supply response to certification-led demand. These moves foreshadow a market where operational execution and certification readiness will define winners.
What’s inside the full PW Consulting report (practical content)
-
Methodology and transparent assumptions — including demand-driver modeling, price-sensitivity scenarios, and feedstock price pass-through mechanisms.
-
Bottom-up market sizing (historical 2020–2025 and forecast 2026–2032) with sensitivity bands and scenario overlays that stress-test demand under varying regulatory and raw-material environments.
-
Commercial diligence modules — supplier scorecards, certification readiness assessments, contract archetypes, and a supplier risk heatmap suitable for procurement negotiations.
-
Go-to-market playbooks for entrants and incumbents — tailored to scale players, bio-based challengers, and distributors aiming to expand into regulated channels.
-
M&A and partnership screening — a prioritized shortlist of target profiles, valuation heuristics, and a roadmap for integration of quality systems and certification pipelines.
-
Operational playbooks — detailed capex/opex scenarios for debottlenecking, capacity additions, and co-location strategies with feedstock suppliers.
Strategic recommendations for 2026
-
Map demand by specification, not by broad application buckets. Procurement and commercial functions must identify which customers require certified bio-origin or pharmacopeial grades and prioritize those relationships for premium allocation.
-
Pursue feedstock optionality. Contracts and co-investments that enable switching between synthetic and bio-based routes (or hedging feedstock exposure) will materially reduce margin volatility.
-
Capitalize on certification as a differentiator. Invest selectively in third-party certification and traceability systems; their commercial payback is accelerated when linked to long-term offtake agreements.
-
Design contracts with embedded sustainability and compliance KPIs. Buyers and suppliers should codify testing frequencies, chain-of-custody requirements, and penalty/bonus structures to align incentives.
-
Use phased capacity plays. Where demand visibility is limited, favor modular debottlenecking and tolling arrangements over greenfield commitments to protect balance sheet flexibility.
Limitations of this preview and next steps
This preview intentionally omits the granular geographic and application splits, proprietary price series, and the detailed company-level revenue estimates that form the core of the full intelligence package. Those subsegment tables and supplier scoring matrices are essential for transaction diligence, detailed sourcing tender design, and regionally differentiated pricing strategies — and they are included exclusively in the full PW Consulting report.
For 2026 planning cycles, executives should use this analysis to align strategic priorities, while commissioning the full report to obtain the granular inputs required for contracting, capex approval, and commercial negotiations. PW Consulting can provide tailored workshops to translate the report’s scenarios into board-ready investment cases and procurement RFx templates.
Contact PW Consulting to access the full study and the proprietary dataset that underpins our forecasts, scenario models, and supplier risk assessments. The decision window in 2026 rewards those who combine rigorous macro foresight with granular, execution-ready intelligence — that is the core value PW Consulting delivers.
For detailed analysis of this topic, please visit the official page: 1,3-butylene Glycol (CAS 107-88-0) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Heavy Bag Stands Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused, practice-oriented preview of our new Heavy Bag Stands Market study — tailored to equip executives, product leaders, and corporate strategists for high-stakes decisions in 2026. This briefing highlights the report’s strategic value, the macro trajectory of the market, competitive fault lines, and the practical intelligence you can deploy immediately. To preserve the commercial value of proprietary segmentation and scenario outputs, select granular splits are intentionally withheld from this preview; the full dataset and model access are available on our report landing page.
Heavy Bag Stands Market
Why this study matters in 2026
The heavy bag stands market sits at the intersection of home fitness expansion, commercial gym refurbishment cycles, and a resurgent combat-sports culture. Our 2025 base-year market assessment values the global market at approximately 103.62 Million USD, with our forward-looking model projecting growth to roughly 139.0 Million USD by 2032 driven by a steady compound annual growth rate (CAGR) of 4.12% across 2026–2032.
Heavy Bag Stands Market
For 2026 corporate planning, this translates into three immediate imperatives:
Heavy Bag Stands Market
- Focus resource allocation on modular, serviceable product architectures that balance compact home-use designs with gym-grade durability.
- Prioritize channel strategies that harmonize direct-to-consumer e-commerce with selective trade-partner relationships in commercial fitness verticals.
- Adopt supply-chain playbooks that mitigate steel-price and logistics volatility while preserving warranty and safety credentials that buyers value.
What the report delivers — practical, transaction-ready intelligence
This market study is built for decision velocity. It is not a high-level brochure; it is a toolkit for commercial execution. Highlights include:
- Market sizing and validated demand trajectories (2020–2025 historical series; 2026–2032 forecast) with scenario-based sensitivities tied to macro inputs such as steel commodity pricing and gym-capEx cycles.
- Commercial segmentation frameworks (product type, distribution channel, and application) that map to buyer personas and procurement drivers — presented as action matrices for product managers and channel leads.
- Unit economics and cost build-ups for reference designs, including BOM sensitivity tables for key tubing and base components commonly used in heavy bag stands.
- Go-to-market playbooks: prioritized channel mixes by go-to-market maturity, sample pricing ladders, promotion calendars for seasonal peaks, and partnership templates for gym chains and fitness event sponsors.
- Supply-chain and manufacturing diagnostics: supplier archetypes, nearshoring vs. offshore break-even templates, and inventory buffers tuned to typical lead times in metal fabrication and powder-coating operations.
- Regulatory and warranty benchmarking: a compliance checklist for safety standards and warranty structures that align with premium positioning in North American and developed-market gyms.
- M&A and product-portfolio scorecards: target criteria and valuation heuristics for roll-up strategies in a fragmented supplier landscape.
Market structure and competitive dynamics — what to watch
The heavy bag stands market is structurally fragmented, with a modest combined share held by the largest manufacturers. Our concentration metrics indicate that the top three players account for a minority share of the market, and the top five still leave substantial share for mid-tier and regional suppliers. This fragmentation creates room for consolidation plays, but any M&A strategy must reckon with variant product architectures, warranty burdens, and localized distribution networks.
Key competitors profiled in the study — each illustrative of a strategic archetype — include:
- Titan Fitness (United States) — a value-to-durability player emphasizing adjustable steel-post designs and reinforced baseplates suited for both home users and light commercial settings.
- Ringside (United States) — a legacy combat-sports brand offering both wall-mounted hardware and free-standing frames with add-on modules such as speed-bag platforms, positioning them in professional training channels.
- Prolast / PROFIGHTSHOP (United States) — heavy-duty, professional-grade stands (including multi-bag frames) that underpin gym and academy purchasing decisions and place emphasis on warranty and lifecycle service.
- Everlast (United States) — a global sports brand that integrates adjustable heavy bag stands into broader equipment portfolios, leveraging brand recognition and distribution reach.
- Century (India) — a regionally strong manufacturer that showcases how localized production and cost-competitive tubular-steel construction can capture latent demand in emerging markets.
- Outslayer (United States) — premium, “made-in-USA” heavy-duty stands built for very high-capacity bags and long warranty tenures, an archetype for premium positioning.
- Balazs (United States) — nimble specialist serving niche demand with universal single-station stands and mounting hardware for bespoke installations.
Each of these firms illustrates different go-to-market vectors: premium domestic manufacturing with long guarantees; legacy brands bundling hardware into broader packages; modular multi-bag systems targeted at academies; and cost-focused regional manufacturers targeting price-sensitive home users. Our competitive heat maps and product-feature parity matrices — detailed in the full report — show where value-based differentiation or technical superiority deliver the highest margin capture.
Supply-side realities and product design signals
From an engineering and procurement perspective, the market’s baseline product architecture is consistent: powder-coated steel tubing with reinforced bases engineered to support a spectrum of bag weights. Adjustable freestanding stands that reach near 8'6" are now commonplace, addressing both adult training and varying bag profiles. Premium manufacturers extend structural warranties of 10–15 years and emphasize domestic fabrication quality as a differentiator for commercial buyers.
Three product design themes emerge as investment priorities in 2026:
- Modularity — frames and add-on modules (speed-bag platforms, extra pegs, anchoring systems) that allow one SKU to target multiple buyer personas with minimal production complexity.
- Serviceability — designs that trade marginal manufacturing cost for lower lifetime-support costs (e.g., replaceable wear plates, standardized fasteners), which is attractive to gym procurement teams focused on total cost of ownership.
- Compact-pack logistics — folding or disassemblable frames that reduce freight and last-mile costs for DTC channels without compromising perceived robustness.
Demand-side and channel playbook
Demand is being pulled by two parallel trends: the maturation of the home-fitness consumer (seeking durable, space-efficient solutions) and a steady rebound of professional training venues investing in equipment refreshes. This duality requires manufacturers to run bifurcated strategies: a premium, service-backed offer for commercial buyers and a value-engineered SKU set for e-commerce-first households.
Effective 2026 channel strategies we recommend:
- Channel tiering: dedicated commercial account managers and extended warranty and spare-parts services for gym chains versus optimized DTC packaging, online content, and cross-sell to home-fitness ecosystems.
- Trade and event activation: leverage industry exhibitions and combat-sports showcases to demonstrate durability claims and secure volume contracts — note that trade events in 2026 remain a productive channel for business development.
- Partnerships with equipment-as-a-service operators: explore rental or subscription models for boutique studios where capital light acquisition is a constraint.
Regulatory, cost, and risk considerations
Key risk vectors that materially affect 2026 outcomes include raw material price volatility (notably steel tubing), warranty claim rates, and logistics lead-time disruptions. Our report quantifies the sensitivity of gross margin to ±10% swings in steel input costs and offers hedging and supplier diversification playbooks to stabilize unit economics.
Safety and warranty benchmarking shows that premium US-made product offers are differentiated by 10–15 year warranty commitments and tighter safety testing — a defensible positioning for B2B procurement but costlier to sustain in a low-margin DTC play.
What you can do in the next 90 days
For senior leaders preparing 2026 budgets and growth plans, three executable moves are high-impact and low regret:
- Run a SKU rationalization using our product feature-value matrix to identify 1–2 high-margin configurable SKUs that can be rapidly brought to market or re-priced for improved profitability.
- Initiate supplier re-qualification for critical tubing and baseplate components, including a dual-sourcing pilot to limit single-supplier exposure to price and lead-time shocks.
- Test a hybrid channel pilot that bundles a service warranty extension for gym customers, and measures CAC and payback period against pure DTC campaigns.
Closing — what this preview leaves out (and why)
This preview provides strategic lenses, competitor archetypes, macro forecasts, and immediate playbooks intended to accelerate decision-making in 2026. To protect the commercial utility of our granular research — including detailed regional & application splits, SKU-level price curves, buyer personas, and downloadable financial models — we intentionally withhold certain granular tables from this public preview. Those datasets translate our 4.12% CAGR forecast and 2025 market base into executable financial scenarios and are available through the full report package.
For market-entry strategies, M&A screening, or a tailored workshop that applies these findings to your product roadmap or channel strategy, contact PW Consulting for priority access and a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Heavy Bag Stands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com